Best Annuity Companies in 2026: 9 Companies Compared
By ToolNimba Editorial Team October 30, 2026 10 min read

- Top pick
 Nationwide
Widest annuity range
Starting priceSee websiteCheck out NationwideRead our review - Runner-up
 New York Life
Lifetime income and stability
Starting priceSee websiteCheck out New York LifeRead our review - Also great
 MassMutual
Long-term stability
Starting priceSee websiteCheck out MassMutualRead our review
How we researched this
We compared official pricing and feature pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Nationwide, New York Life and MassMutual stand out for range, long histories and strong financial strength ratings reported in public comparisons.
- The right company depends first on the annuity type you need, fixed, fixed indexed, variable or lifetime income, not on a headline rate alone.
- Surrender periods, fees and state availability can change the value of a contract more than a small difference in an illustrated rate.
- Smaller or online-focused issuers can offer competitive fixed rates, but check the issuer rating and withdrawal terms before you commit.
- This is not financial advice. Annuity terms vary by state and contract, and surrender charges may apply if you withdraw early.
Quick comparison
| Name | Best for | Starting price | Free plan | |
|---|---|---|---|---|
| Nationwide | Widest annuity range | See website | No | Visit |
| New York Life | Lifetime income and stability | See website | No | Visit |
| MassMutual | Long-term stability | See website | No | Visit |
 Allianz Life | Fixed indexed annuities | See website | No | Visit |
 Athene | Fixed and indexed accumulation | See website | No | Visit |
 Pacific Life | Variable and indexed choice | See website | No | Visit |
 Lincoln Financial | Retirement income planning | See website | No | Visit |
 Prudential | Income and variable options | See website | No | Visit |
 Gainbridge | Low-cost online fixed annuities | See website | No | Visit |
The best annuity companies
An annuity is a contract with an insurer, not a bank account. You pay a premium, and in return you may get tax-deferred growth, a future income stream, or both, depending on the contract. The companies below cover the main contract types US buyers usually compare.

Nationwide is our pick for buyers who want to compare several annuity types from one insurer. Its range covers fixed, fixed indexed and variable contracts, plus income options that can be added through riders on eligible products. That breadth helps when you are not yet sure which structure fits your retirement plan.
The trade-off is complexity. A variable annuity with investment options and riders will read very differently from a simple fixed contract, and fees can differ a lot between them. Ask for the full fee schedule, the surrender period and the exact income calculation before you sign, and compare those points with at least one other insurer on this list.
- Broad range of fixed, indexed and variable annuities
- Large, well-known insurer
- Income riders available on many contracts
- Product details vary by state
- Variable contracts can carry fees that need careful review

New York Life appeals to buyers who put payout reliability first. As a mutual insurer, it is owned by policyholders rather than public shareholders, and public comparisons often cite its financial strength and its immediate and deferred income annuities. If your main goal is a steady monthly check in retirement, this is a sensible place to start.
The catch is access. You will often need to work with a professional to get a quote and compare income illustrations, which takes more time than an online quote. That is not a reason to avoid it, but it does mean you should ask how the payout changes with age, single or joint life, and any period-certain option.
- Mutual company structure
- Long history
- Immediate and deferred income annuities
- Many products are sold through financial professionals
- Online detail can be limited
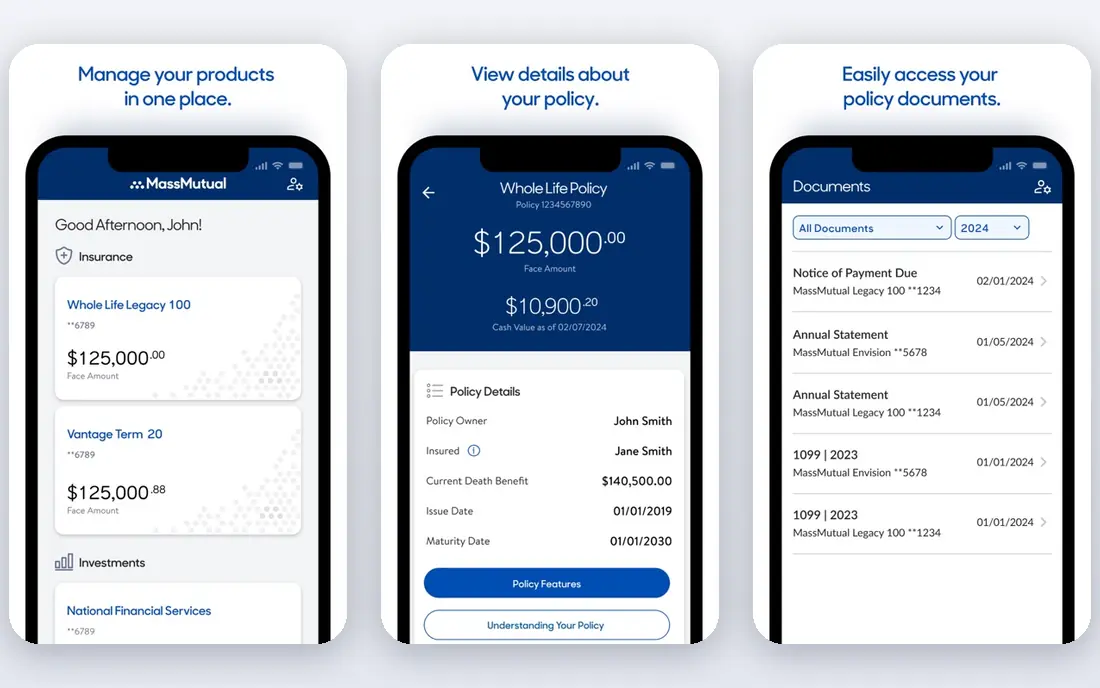
MassMutual is a strong choice for buyers who want a conservative, long-lived insurer behind a long-term promise. Public comparisons cite an A++ rating from AM Best for MassMutual, the top rating in that scale, and its product set spans fixed deferred, fixed indexed, variable and income annuities. That combination suits people who want growth potential with a well-capitalized issuer.
Minimums and availability still matter. Some contracts start at lower premiums than others, and fixed deferred products have been reported with higher minimums than some rivals. Confirm the minimum for the exact contract you are considering, not just the brand as a whole.
- High financial strength rating reported in public comparisons
- Fixed, indexed and variable options
- Income annuities available
- Minimum premiums vary by product
- Some details require an agent quote
Allianz Life is best known in this group for fixed indexed annuities, where returns are linked to an index but principal is protected from market falls. Buyers who want some market-linked upside without direct market exposure often start here. The company also offers index variable annuities, which add more market exposure and more risk.
Read the index terms closely. Caps, participation rates and spreads limit how much index gain you keep, and those terms can change at renewal in some contracts. A strong first-year illustration does not guarantee the same terms later, so ask which terms are fixed and which can change.
- Large fixed indexed range
- Index-linked options
- Income riders on eligible contracts
- Some contracts have long surrender periods
- Index credits are capped or limited by participation rates
Athene is one of the largest annuity sellers in the US by sales in recent industry rankings, and it covers immediate, fixed, fixed indexed and registered index-linked contracts. Buyers focused on accumulation often look at Athene for multi-year guaranteed rates and indexed growth options in one place.
State availability is the main practical check. Not every Athene product is sold in every state, and rates can differ by state and premium amount. Get a quote for your state and your premium band, and check the free withdrawal allowance before you compare rates with other issuers.
- Wide range of fixed, indexed and income annuities
- Competitive fixed rates in recent rate tables
- No annual contract fee on many products as reported
- Product availability varies by state
- Customer review scores are mixed in public sources
Pacific Life suits buyers who want investment choice inside an annuity wrapper. Its variable annuities offer a range of investment options, while its indexed and income contracts give more conservative paths for other parts of a retirement plan. That mix can work well when one household wants different risk levels for different goals.
Variable annuities deserve extra care here. Mortality, expense and rider fees can add up, and investment results are not guaranteed. If you choose this route, compare total annual costs and the income rider terms with a simpler fixed or indexed contract before you decide.
- Variable, fixed indexed and income annuities
- Long operating history
- Flexible income options
- Variable contract fees and investment choices need close review
- Some products are advisor-sold
Lincoln Financial is a useful pick for buyers building a retirement income plan rather than buying a single product in isolation. Its range includes fixed, fixed indexed and variable annuities, and several contracts offer riders aimed at lifetime income or legacy goals. That makes it a good second quote when you are weighing income against growth.
The downside is comparison effort. Rider names and benefit calculations differ from insurer to insurer, so two income illustrations may not be directly comparable. Ask each insurer for the same inputs, same age, same premium, same start date, and same single or joint life basis, so the comparison is fair.
- Fixed, indexed and variable annuities
- Income-focused riders
- Estate planning options on some contracts
- Product names and rider terms can be hard to compare
- Pricing requires a quote
Prudential fits buyers who want a large insurer and a choice between income-focused and market-linked contracts. Its annuity business sits alongside life insurance and retirement services, which can help if you want income, protection and investment planning discussed together rather than in separate silos.
As with other advisor-sold ranges, you should expect to discuss your full retirement picture before a recommendation. That can be a benefit if the advice is good, but it also means the sales process may take longer. Keep the focus on the contract terms, the surrender period and the total cost, not only on the projected income figure.
- Large insurer with income and variable annuities
- Investment and retirement planning support
- Well-known brand
- Some annuities are only available through advisors
- Fee structures vary widely by contract
Gainbridge is the outlier here, and that is its appeal. It sells fixed annuities online with a simpler process and, on its fixed products, no sales or administrative fees as reported in public comparisons. Buyers who already know they want a multi-year guaranteed fixed annuity and who are comfortable buying online may find this the fastest route.
The range is narrower, so it will not suit someone who wants variable investment choice or a complex income rider. Check the issuer rating, the surrender schedule and the annual free withdrawal amount, which has been reported at up to 10 percent on some products, before you judge it only on rate.
- Online purchase process
- Low minimums reported on some products
- No sales or administrative fees as reported for its fixed products
- Narrower product range than large insurers
- Fewer investment options
How we picked these
We compared official product pages, pricing and rate tables, public financial strength ratings, industry sales rankings and public reviews. We favored insurers that sell more than one annuity type, that are widely available in the US, and that publish clear product information. We did not test contracts ourselves, and we did not accept a headline rate as proof of value without checking surrender terms and state availability.
What to check before you buy an annuity
Start with the type, not the company. A fixed annuity suits capital preservation and a known rate for a set term. A fixed indexed annuity adds index-linked upside with caps. A variable annuity adds market exposure and fees. An immediate or deferred income annuity suits a guaranteed paycheck, but it usually gives up flexible access to the lump sum.
Next, check four contract facts. First, the surrender period and charge schedule, and how much you can withdraw each year without a charge. Second, all fees, including rider fees on variable and indexed contracts. Third, the financial strength rating of the issuing insurer and the state guaranty limits that apply in your state. Fourth, tax treatment, since withdrawals are generally taxed as ordinary income and early withdrawals before age 59 and a half may face an extra tax penalty. This is not financial or tax advice, and annuity terms vary, so get a written illustration for your age, state and premium before you commit.
Sources
- https://www.nationwide.com
- https://www.newyorklife.com
- https://www.massmutual.com
- https://www.allianzlife.com
- https://www.athene.com
- https://www.pacificlife.com
- https://www.lincolnfinancial.com
- https://www.prudential.com
- https://www.gainbridge.life
- https://bestguide.com/buyersguide/best-annuities-companies/
- https://www.annuity.org/providers-paid/