Best Buy Now Pay Later Apps in 2026: 9 Apps Compared
By ToolNimba Editorial Team October 30, 2026 12 min read

- Top pick
 Klarna
Flexible plans
Starting priceFreeCheck out KlarnaRead our review - Runner-up
 Affirm
Larger purchases
Starting priceFreeCheck out AffirmRead our review - Also great
 Afterpay
Simple Pay in 4 shopping
Starting priceFreeCheck out AfterpayRead our review
How we researched this
We compared official pricing and feature pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Pay in 4 plans are usually interest-free when paid on time, but late fees, longer monthly plans and stacked plans can still make a purchase costly.
- Affirm stands out for larger purchases and longer terms, with no late fees, while its monthly plans can carry an APR of up to 36 percent.
- Klarna offers the widest mix of plans, from Pay in 4 to monthly financing, while Afterpay keeps the structure simple with four biweekly payments.
- PayPal Pay in 4 suits people who already use PayPal, and Shop Pay Installments suits frequent Shopify shoppers.
- This is not financial advice. Treat BNPL as a payment schedule, not extra income, and only split a purchase you could afford without it.
Quick comparison
| Name | Best for | Starting price | Free plan | |
|---|---|---|---|---|
| Klarna | Flexible plans | Free | Yes | Visit |
| Affirm | Larger purchases | Free | Yes | Visit |
| Afterpay | Simple Pay in 4 shopping | Free | Yes | Visit |
 PayPal Pay in 4 | Existing PayPal users | Free | Yes | Visit |
 Sezzle | Budget shoppers | Free | Yes | Visit |
 Zip | Shopping anywhere Visa is accepted | Free | Yes | Visit |
 Shop Pay Installments | Shopify shoppers | Free | Yes | Visit |
 Splitit | Using an existing credit card | Free | Yes | Visit |
 Perpay | Paycheck-based repayment | Free | Yes | Visit |
The best buy now pay later apps
Buy now, pay later apps split a purchase into smaller payments, usually four payments over six weeks. The appeal is clear: you get the item now and spread the cost. The risk is also clear: several small plans can add up to a large monthly total, and a missed payment can bring fees or credit reporting, depending on the plan. We compared official terms, fee pages and public comparisons, and we focused on what each app charges when a plan goes wrong, not just when it goes right.
Klarna is the most flexible BNPL app in this list, because it offers more than one way to pay. Pay in 4 splits a purchase into four interest-free payments, Pay in 30 lets you pay the full amount within 30 days, and monthly financing covers larger purchases over a longer term. That range helps when a single Pay in 4 schedule does not fit your pay cycle.
The flexibility needs care. Monthly plans are not the same as Pay in 4, and interest can apply. Klarna also charges a late fee of up to $7 on Pay in 4 if a payment remains unpaid 10 days after it was due, capped at 25 percent of the purchase. Check the plan type at checkout, because the cheapest option is almost always the short interest-free plan paid on time.
- Pay in 4, Pay in 30 and monthly plans
- Wide retailer coverage
- App and browser extension for checkout
- Late fee of up to $7 on Pay in 4 in the US
- Longer plans can carry interest up to 35.99 percent APR
Affirm is our pick for larger purchases, because it is built for longer repayment rather than only four quick payments. You see the total interest cost before you commit, and Affirm states that it charges no late fees. That transparency helps when you are comparing a $1,000 purchase across several months, rather than guessing at hidden charges.
Affirm also offers Pay in 4 at 0 percent APR for smaller purchases. The catch is the monthly APR range, from 0 percent to 36 percent depending on retailer and credit profile. A long term at a high APR can add a large amount, so compare the total paid, not just the monthly payment.
- No late fees
- 0 percent APR available at select retailers
- Terms up to 60 months for larger purchases
- Monthly plan APR can reach 36 percent
- Approval and limit depend on credit and purchase
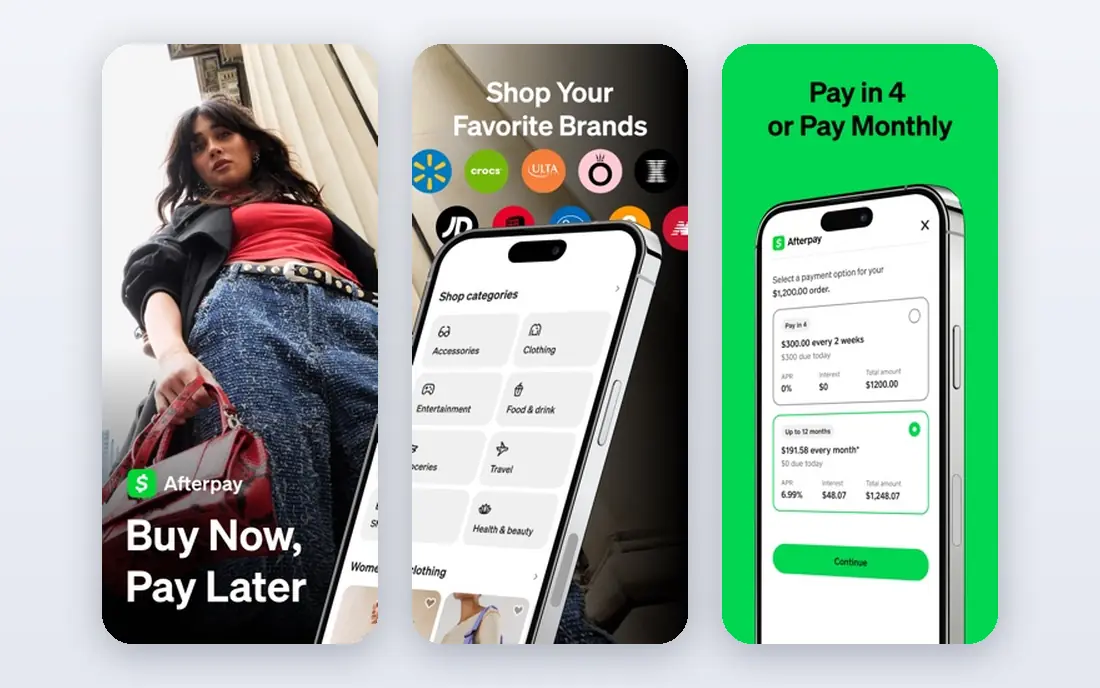
Afterpay keeps BNPL simple. Most purchases split into four equal payments every two weeks, with no interest when paid on time. That predictability suits shoppers who want a clear schedule and who shop with retailers that offer Afterpay, including many fashion, beauty and lifestyle brands. An in-store card in the app also lets you use Afterpay at physical stores that accept it.
The simplicity does not remove risk. A late payment can cost up to $8, charged once it is 10 days overdue, capped at 25 percent of the order. Spending limits vary and grow with on-time history. Keep open plans low, because four plans at once can feel very different from one plan alone.
- Simple four-payment structure
- Interest-free when paid on time
- Strong fashion and lifestyle retailer coverage
- Late fee of up to $8 per missed payment, capped at 25 percent of the order
- Spending limits vary by user
PayPal Pay in 4 is the easiest BNPL option for people who already pay with PayPal. It splits eligible purchases from $30 to $1,500 into four interest-free payments over six weeks, with no late fees on Pay in 4. Because it sits inside a PayPal account many shoppers already have, there is no new app to learn and no new retailer network to check.
Pay in 4 is for smaller purchases, and PayPal monthly plans for larger amounts can carry interest, with APRs reported from 9.99 percent upward. That makes PayPal strong for everyday purchases, but weaker for a large purchase where Affirm offers longer terms. Treat the limit as a guardrail, not a target.
- No late fees on Pay in 4
- Familiar PayPal checkout
- Works for purchases from $30 to $1,500
- Monthly plans can carry APR from 9.99 percent
- Pay in 4 limit is lower than Affirm for large purchases
Sezzle is built for budget shoppers who want a clear Pay in 4 plan and a little flexibility when payday shifts. The core plan is interest-free, and one free reschedule per order can move a payment without a fee, which helps when a paycheck lands a few days later than expected. Sezzle Up, an optional feature, can report on-time payments for credit building, though it is not automatic for every user.
The fees need attention. Some plans carry service fees of up to $7.49, and late fees can reach $16.95, capped at 25 percent of the order total. That makes Sezzle cheaper than a high-APR monthly plan when paid on time, but more expensive than Affirm or PayPal if a payment slips. Use the reschedule feature early if you see a problem coming, rather than waiting for a late fee.
- Interest-free Pay in 4
- One free reschedule per order
- Optional credit building through Sezzle Up
- Service fees of up to $7.49 may apply on some plans
- Late fees up to $16.95, capped at 25 percent of the order
Zip, formerly Quadpay, solves a common BNPL frustration: the store you want does not offer your BNPL app. Zip generates a virtual Visa card for a purchase, so you can use it at many stores that accept Visa, even without a direct BNPL partnership. That freedom is useful for everyday purchases, gifts and stores outside the usual BNPL networks.
The trade-off is a small fee on many plans, typically $1 per installment, or $4 per order. A late fee of about $7 per missed payment can also apply. Zip is still interest-free on Pay in 4 when paid on time, but it is not quite free in the way Afterpay is for on-time payers.
- Virtual Visa card works at many stores, not only partner retailers
- Simple Pay in 4 structure
- Fee of $1 per installment, or $4 per order, on many plans
- Late fee reported at $7 per missed payment
Shop Pay Installments is the BNPL option built into Shopify checkout, so it appears naturally when you shop at a Shopify store. Pay in 4 is interest-free, and monthly installments are available for larger purchases, with APRs reported from 10 percent to 36 percent depending on the plan. For frequent Shopify shoppers, the checkout experience is faster than opening a separate BNPL app.
The limit is coverage. Shop Pay Installments only helps at stores that use Shop Pay, so it is not a general-purpose BNPL app like Klarna or Zip. It is best treated as a convenient option inside Shopify, not as your only BNPL tool. As with Affirm, compare the total cost on monthly plans, because a low monthly payment over a long term can hide a large interest total.
- Smooth checkout on Shopify stores
- Pay in 4 at 0 percent
- Monthly plans for larger purchases
- Only useful at stores using Shop Pay
- Monthly plan APR can range from 10 percent to 36 percent
Splitit takes a different approach. Instead of offering a new line of credit, it splits a purchase across your existing credit card, with installments charged to that card over time and no interest from Splitit itself. That appeals to shoppers who do not want another credit account, another app balance, or another approval process.
The catch is that you still need available credit on your card, and your card issuer may charge interest if you do not pay the card balance in full. Splitit does not remove credit card interest, it only spreads the purchase. It is a good fit for cardholders with a healthy credit limit and a habit of paying the card in full, and a poor fit for anyone already carrying a card balance.
- Uses your existing credit card, with no new credit application
- 0 percent interest on installments
- No late fee structure like other BNPL apps
- Requires available credit on your card
- Fewer retailer partnerships than Klarna or Afterpay
Perpay is designed for shoppers who want repayment tied to their paycheck rather than to a card or bank debit. Users set up direct deposit through their employer, and Perpay purchases are repaid from incoming pay over time. The marketplace lets users shop for clothing, electronics and home goods inside the Perpay system, with spending limits based on verified income.
That payroll link is both the strength and the limit. It can help people with thin or no credit history, because Perpay does not rely on a traditional credit check for its core product. It is less flexible outside Perpay, and changing jobs can complicate repayment, so read the payroll terms before you sign up.
- Repayment through paycheck direct deposit
- No credit check for the core product
- Marketplace for shopping
- Repayment is tied to payroll setup
- Less flexible than Pay in 4 apps for one-off purchases
How we picked these
We compared official fee and plan pages, app store listings and public comparisons, and we selected apps that are available in the US in 2026 and that offer a clear Pay in 4 or installment structure. We favoured apps with transparent fee terms, wide retailer coverage or a distinct repayment model, and we noted where late fees, service fees or APR ranges apply. We did not claim hands-on testing, and we treated APR ranges and limits as ranges that vary by retailer, purchase and credit profile.
How to choose a buy now pay later app
Start with the purchase, not the app. Write down the total price, the payment dates, and what happens if a payment is late. A 0 percent Pay in 4 plan paid on time is usually the cheapest BNPL option, while a monthly plan at a high APR can cost more than waiting or using a lower-cost payment method.
Count open plans, not just one plan
The most common BNPL problem is stacking. Three or four Pay in 4 plans, each with a payment every two weeks, can add up to a large total on a single payday. Before you add a plan, add up all upcoming BNPL payments for the next six weeks and compare that total to the money left after rent, bills and food. If the total is tight, skip the purchase or choose a longer Affirm term with a clear total cost.
Check fees, APR and credit reporting
Read the late fee, service fee and APR for the exact plan at checkout, because Pay in 4 and monthly plans have different terms. Some apps report monthly plan activity to credit bureaus, while Pay in 4 reporting varies. A missed payment that goes to collections can harm your credit, even if the app itself does not report every on-time payment. If building credit is your goal, choose an app and plan that reports on-time payments, and pay every installment on time.
Use BNPL for planned purchases
BNPL works best for a planned purchase you already budgeted for. It works worst for impulse purchases, because the first payment feels small while the total commitment is larger. This is not financial advice, and if BNPL debt is growing, a nonprofit credit counsellor can help you review options.
Sources
- https://www.klarna.com
- https://www.affirm.com
- https://www.afterpay.com
- https://www.paypal.com
- https://sezzle.com
- https://zip.co
- https://shop.app
- https://www.splitit.com
- https://perpay.com
- https://www.moneylion.com/learn/personal-loans/buy-now-pay-later/best-buy-now-pay-later-apps
- https://hanahow.com/guides/missed-buy-now-pay-later-payment/