Best Credit Builder Apps in 2026: 8 Apps Compared
By ToolNimba Editorial Team November 10, 2026 9 min read

- Top pick
 Kikoff
Lowest monthly cost
Starting price$5 per monthCheck out KikoffRead our review - Runner-up
 Self
Building credit and savings together
Starting price$25 per monthCheck out SelfRead our review - Also great
 Chime Credit Builder
No-fee secured card building
Starting priceFreeCheck out Chime Credit BuilderRead our review
How we researched this
We compared official pricing and feature pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Kikoff and Grow Credit offer the lowest-cost starting points, while Self suits people who also want to build savings.
- Chime Credit Builder has no monthly fee, but it requires a Chime checking account and a qualifying direct deposit.
- Experian Boost is free, but it reports only to Experian, so it pairs better with an app that reports to all three bureaus.
- A credit builder app is not financial advice, and results depend on on-time payments, existing credit history, and the scoring model used.
Quick comparison
| Name | Best for | Starting price | Free plan | |
|---|---|---|---|---|
| Kikoff | Lowest monthly cost | $5 per month | No | Visit |
| Self | Building credit and savings together | $25 per month | No | Visit |
| Chime Credit Builder | No-fee secured card building | Free | Yes | Visit |
 Grow Credit | Building credit from subscriptions | Free | Yes | Visit |
 MoneyLion Credit Builder Plus | All-in-one banking and credit building | $19.99 per month | No | Visit |
 Kovo | Reporting to four bureaus | $10 per month | No | Visit |
 Experian Boost | Free Experian-only boost | Free | Yes | Visit |
 Credit Sesame | Score tracking plus credit building tools | Free | Yes | Visit |
The best credit builder apps
We compared official pricing pages, reporting details, and app store listings to find apps that genuinely report payments and fit ordinary US consumers. The list below mixes free starting points with paid plans for people who want a structured loan or a secured card.
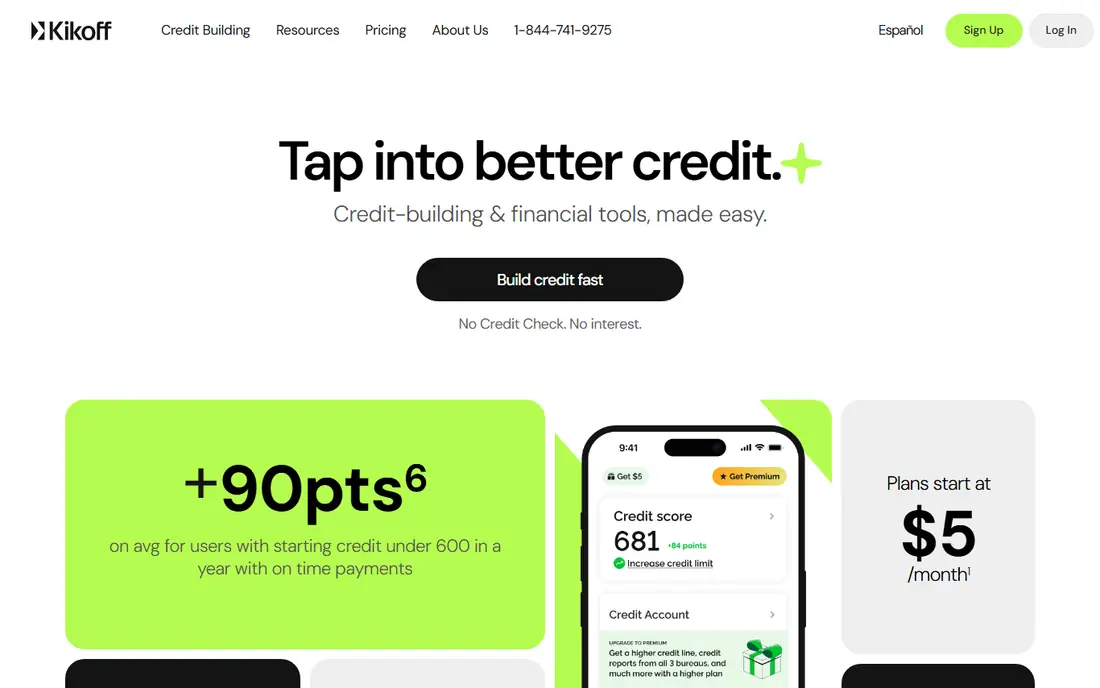
Kikoff is our pick for most people who want to start cheaply and simply. It offers a small revolving credit line that is used for a Kikoff plan, and it reports payments to Equifax, Experian, and TransUnion. That broad reporting matters because each bureau keeps its own file, and an account that reaches only one bureau leaves the other two unchanged.
The catch is scale. A small line does not give you much room to show low utilization, and it will not replace a secured card for everyday spending. Still, for a first account or a thin file, the $5 starting plan is easy to keep up with, and on-time payments are the part that matters most.
- Low monthly cost
- Reports to all three major bureaus
- No hard credit check to sign up
- Small credit line
- Higher plans cost more
- Rent reporting details vary by plan
Self works differently from a card. You make monthly payments on a credit builder loan, and the money is held in a savings account and returned at the end of the term. That structure suits people who want a forced savings habit alongside payment history, and Self reports to all three major bureaus.
The trade-off is cash flow. Plans starting at $25 per month are a real monthly commitment, and you cannot use the loan money while the plan runs. Self also offers a secured card for customers who want revolving credit as well, but that card needs a deposit, so check the current terms before you add it.
- Credit builder loan plus savings payout
- Reports to all three bureaus
- Optional secured card available
- Monthly payments are higher than Kikoff
- Money is locked up until the term ends
- Fees and interest apply
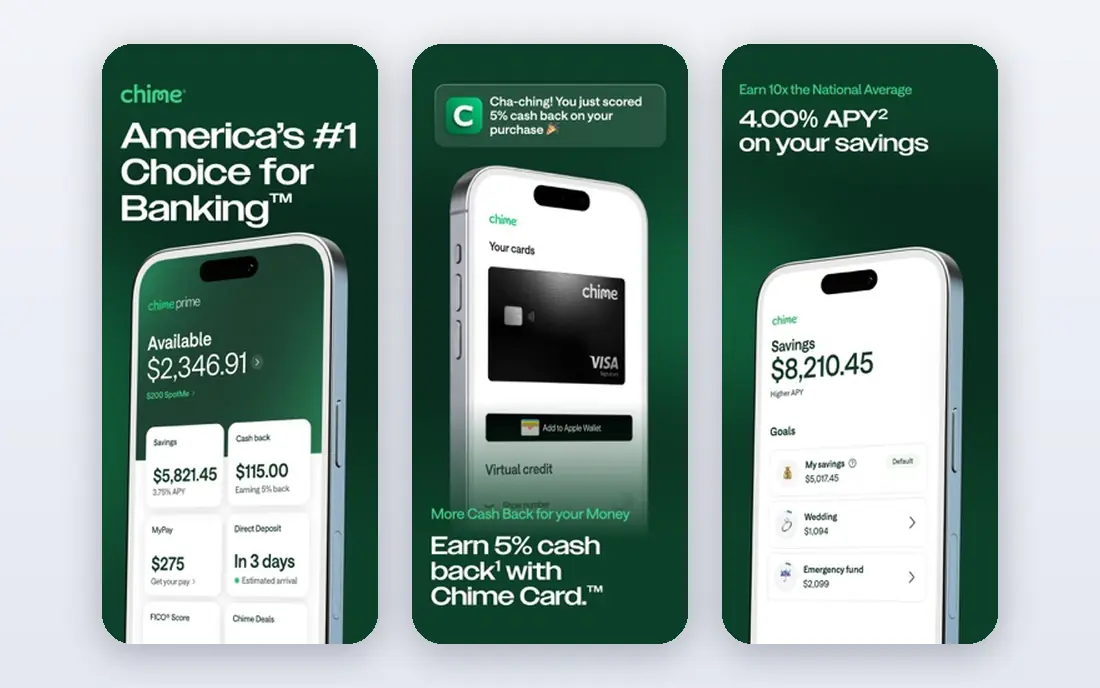
Chime Credit Builder is a secured card designed to remove the usual cost barriers. There is no interest and no annual fee listed, and activity is reported to all three bureaus. You set aside money in your Chime checking account, and that money sets how much you can spend, which helps keep balances under control.
Eligibility is the main limit. You need an active Chime checking account and a qualifying direct deposit, so it is not an option if you bank elsewhere and do not want to switch. If you already use Chime, though, it is one of the strongest no-fee routes to reported payments.
- No annual fee, interest, or minimum deposit stated
- Reports to all three bureaus
- Money moves from a Chime checking account
- Requires a Chime checking account
- Requires a qualifying direct deposit
- Not a standalone app for non-Chime customers
Grow Credit turns payments you already make, such as streaming subscriptions, into reported credit activity. It issues a virtual card for those subscriptions and reports to the major bureaus. That passive approach suits people who do not want a new loan or a new spending habit just to build credit.
The free tier is the place to start, and paid plans raise the limit and add features. The limit is that subscription reporting alone may move a score slowly, especially if you have no other accounts. It works best as a low-effort addition, not as your only credit account.
- Free tier available
- Reports subscription payments
- No hard credit check on the free tier in many cases
- Paid plans cost more for higher limits
- Built around subscriptions, not general spending
- Limits are modest
MoneyLion Credit Builder Plus
Best for: All-in-one banking and credit building
MoneyLion Credit Builder Plus bundles a credit builder loan with a broader financial app that includes banking, budgeting, and investing tools. If you already want that bundle, the credit building piece fits naturally, and payments are reported to all three bureaus.
If you only want credit building, the $19.99 monthly membership is hard to justify against Kikoff at $5 or Grow Credit on its free tier. Our view is simple: pick MoneyLion when you will actually use the wider app, not when you only need one reported account.
- Credit builder loan plus banking and budgeting tools
- Reports to all three bureaus
- Single app for several money tasks
- Monthly membership cost is high for credit building alone
- Features may be more than some users need
- Terms vary by membership tier
Kovo stands out for bureau coverage. Most apps report to three bureaus, while Kovo also reports to Innovis, a fourth bureau used by some lenders and identity checks. At $10 per month, it sits between Kikoff and Self on cost, and it follows an installment plan model rather than a card.
The honest catch is that a fourth bureau helps only if a lender checks that bureau, and many do not. Still, for people who want the widest reporting net at a mid-range price, Kovo is a sensible pick, and the monthly cost stays predictable.
- Reports to Equifax, Experian, TransUnion, and Innovis
- $10 monthly cost
- No interest or fees stated on its core plan
- Smaller brand than Self or Chime
- Plan is installment based, not a card
- Cash back and extras are modest
Experian Boost is free and works by linking bank accounts so that qualifying utility, phone, and streaming payments appear on your Experian credit file. It is the fastest free option here, and it needs no new debt, which makes it a good first step for many readers.
The limit is clear in the name. Only Experian sees the added payments, so lenders who pull Equifax or TransUnion will not see the same boost. Use it alongside an app that reports to all three bureaus, and treat any score change as a possible outcome, not a promise.
- Free to use
- Can add utility and phone payments to your Experian file
- No loan or card needed
- Reports only to Experian
- Only certain recurring payments count
- Score change is not guaranteed
Credit Sesame is best understood as a monitoring app with credit building features, rather than a single credit builder account. The free tier gives you score tracking and analysis, which helps you see whether on-time payments and lower balances are moving in the right direction.
That is useful, but it is not a substitute for a reported account. If you already have a Kikoff, Self, or Chime account, Credit Sesame can help you watch the result. If you have no reported account at all, start with one of those first, then add Credit Sesame for tracking.
- Free score monitoring and credit analysis
- Credit building features available
- Useful for tracking progress over time
- Free tier is mainly monitoring
- Paid features cost extra
- Building tools are less direct than a loan or card
How we picked these
We compared official feature pages, pricing pages, and app store listings, and we favored apps that report to at least one major bureau, publish a clear price, and are available to US consumers in October 2026. We left out apps that only offer score monitoring with no reported account, and we did not count a product as a credit builder just because it mentions credit in its marketing. Prices here reflect the vendor pages and comparison sources we checked, so confirm the current plan before you sign up, since prices and plan limits change.
What to check before you choose
Start with bureau coverage, then cost, then fit. An app that reports to all three bureaus gives you the widest base, while a single-bureau tool like Experian Boost is better as an add-on. Next, check whether the monthly payment fits your budget for at least six to twelve months, because a missed payment can hurt more than a new account helps.
Also check whether you need a bank account switch, a deposit, or a membership to qualify. Chime needs a Chime account, Self locks money into savings, and MoneyLion bundles credit building into a wider membership. Pick the structure you will actually keep paying on time, and set up autopay if the app allows it. This is not financial advice, and a credit builder app does not guarantee a higher score. If you are behind on existing debts, dealing with those first usually matters more than opening a new account.
Sources
Frequently asked questions
What is the best credit builder app for most people?
Kikoff is a strong starting point because it costs $5 per month and reports to all three major bureaus. Self is a better fit if you want savings built in, and Chime Credit Builder is better if you already bank with Chime and want no monthly fee.
What is the best app to build credit with no credit history?
An app with no hard credit check and broad reporting is the safest start, and Kikoff and Chime Credit Builder both fit that description for eligible users. Add Experian Boost for free if you have qualifying utility or phone payments, and keep every payment on time.
Does a credit builder app guarantee a higher credit score?
No. Payment history, amounts owed, length of history, and other factors all feed into a score, and different lenders use different models. On-time payments on a reported account can help over time, but no app can promise a specific score change.
What is the best app to improve a credit score quickly?
There is no reliable quick fix. Experian Boost can show a fast change on an Experian score when qualifying payments are added, but that change is limited to Experian. Steady on-time payments and low balances matter more than any single app.
Can I use more than one credit builder app at once?
Yes, and many people pair a free tool like Experian Boost with one paid reported account. Avoid opening several paid accounts at once, since each monthly payment adds to your budget and a missed payment can undo the benefit.