Best Financial Advisor Companies in 2026: 9 Firms Compared
By ToolNimba Editorial Team November 10, 2026 11 min read

- Top pick
 Facet Wealth
Flat-fee dedicated planning
Starting priceSee websiteCheck out Facet WealthRead our review - Runner-up
 Vanguard Personal Advisor
Low-cost hybrid advice
Starting priceSee websiteCheck out Vanguard Personal AdvisorRead our review - Also great
 Betterment Premium
Automation plus human planners
Starting priceSee websiteCheck out Betterment PremiumRead our review
How we researched this
We compared official pricing and feature pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Facet Wealth suits people who want dedicated planning for a flat monthly fee with no asset minimum, while Vanguard Personal Advisor suits larger portfolios at a low percentage fee.
- Betterment Premium and Schwab Intelligent Portfolios Premium suit investors who want automation plus access to human planners when life changes.
- J.P. Morgan Personal Advisors suits clients who want traditional full-service advice tied to a large bank, while Zoe and Harness help people find or match with an advisor.
- Fees, minimums and the scope of planning differ widely, so compare what is included, such as tax, estate and retirement planning, before you choose.
Quick comparison
| Name | Best for | Starting price | Free plan | |
|---|---|---|---|---|
| Facet Wealth | Flat-fee dedicated planning | See website | No | Visit |
| Vanguard Personal Advisor | Low-cost hybrid advice | See website | No | Visit |
| Betterment Premium | Automation plus human planners | See website | No | Visit |
 Schwab Intelligent Portfolios Premium | Automation plus planner access | See website | No | Visit |
 J.P. Morgan Personal Advisors | Traditional full-service advice | See website | No | Visit |
 Zoe Financial | Advisor matching marketplace | See website | Yes | Visit |
 Harness Wealth | Advisor matching with local options | See website | Yes | Visit |
 Ellevest | Planning with a gender-aware approach | See website | No | Visit |
 SoFi | Low-cost entry to advice | See website | Yes | Visit |
The best financial advisor companies
A good advisor company pairs a clear fee with real planning, not just portfolio picks. These nine firms cover flat-fee planning, low-cost hybrid advice and full-service wealth management for different budgets.
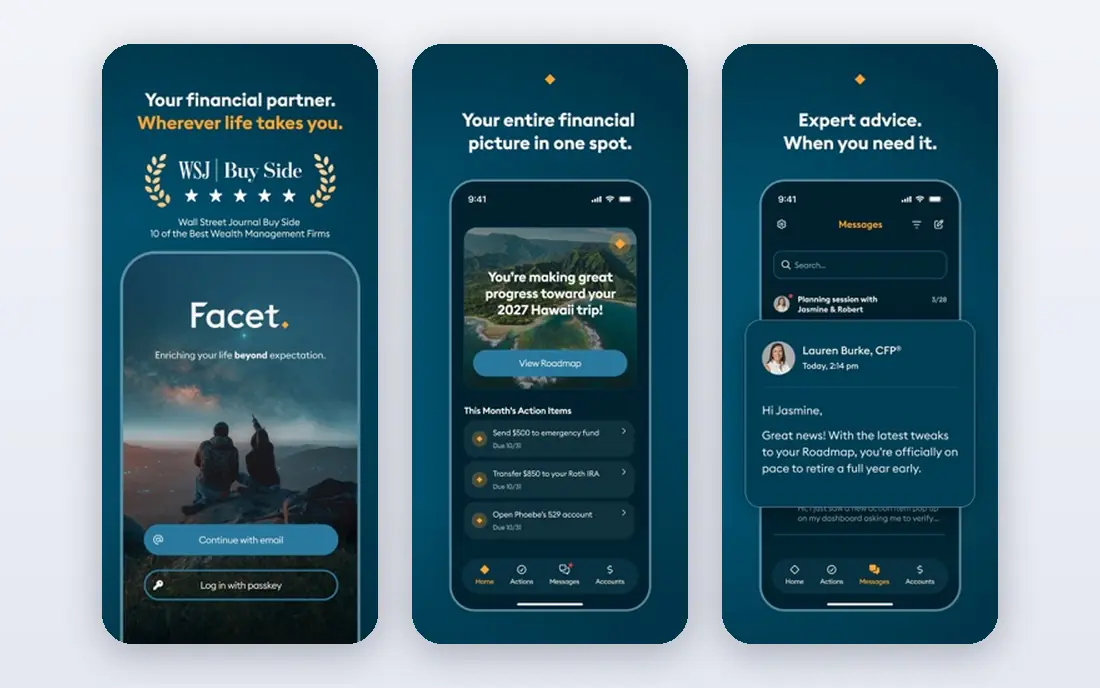
Facet suits people who want an ongoing planner for budgeting, retirement, tax and investing, without handing over a percentage of their portfolio each year. For buyers, the clearest strength is Dedicated certified planners, and that advantage shows up most when the tool is used for flat-fee dedicated planning. Pricing starts at See website, with a free plan listed as No, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is flat monthly fee. The honest catch is Fee can be high for very small balances, and a second limit to weigh is no in-person branches. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Dedicated certified planners
- Flat monthly fee
- No asset minimum
- Broad planning
- Fee can be high for very small balances
- No in-person branches

Vanguard Personal Advisor suits investors with at least $50,000 who want human advice and low-cost funds, without paying a traditional wealth manager fee. For buyers, the clearest strength is Human advisors plus low-cost Vanguard funds, and that advantage shows up most when the tool is used for low-cost hybrid advice. Pricing starts at See website, with a free plan listed as No, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is retirement and tax planning. The honest catch is Minimum of $50,000 in many cases, and a second limit to weigh is service is mostly remote. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Human advisors plus low-cost Vanguard funds
- Retirement and tax planning
- Clear fee model
- Minimum of $50,000 in many cases
- Service is mostly remote

Betterment Premium suits hands-off investors who want automation day to day, plus a planner to call when retirement, a house purchase or a career change arrives. For buyers, the clearest strength is Automated portfolios with tax features, and that advantage shows up most when the tool is used for automation plus human planners. Pricing starts at See website, with a free plan listed as No, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is access to certified planners. The honest catch is Premium minimum is $100,000, and a second limit to weigh is advice is mainly digital. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Automated portfolios with tax features
- Access to certified planners
- Goal planning
- Premium minimum is $100,000
- Advice is mainly digital
Schwab Intelligent Portfolios Premium
Best for: Automation plus planner access
Schwab Premium suits Schwab customers who want a blend of automation and human advice, with a one-time planning fee and an ongoing asset-based fee. For buyers, the clearest strength is Automated investing with certified planner access, and that advantage shows up most when the tool is used for automation plus planner access. Pricing starts at See website, with a free plan listed as No, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is tax-loss harvesting. The honest catch is Planning fee plus asset fee, and a second limit to weigh is $25,000 minimum. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Automated investing with certified planner access
- Tax-loss harvesting
- Broad Schwab tools
- Planning fee plus asset fee
- $25,000 minimum
J.P. Morgan Personal Advisors
Best for: Traditional full-service advice
J.P. Morgan Personal Advisors suits clients who want traditional, full-service wealth management and already bank or invest with J.P. Morgan. For buyers, the clearest strength is Dedicated advisor team, and that advantage shows up most when the tool is used for traditional full-service advice. Pricing starts at See website, with a free plan listed as No, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is full wealth planning. The honest catch is Higher minimums and fees than hybrid rivals, and a second limit to weigh is best for larger clients. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Dedicated advisor team
- Full wealth planning
- Bank and brokerage links
- Higher minimums and fees than hybrid rivals
- Best for larger clients
Zoe suits people who do not know where to start, because it narrows vetted advisors by goals, location and fee model before any intro call. For buyers, the clearest strength is Matches clients with vetted advisors, and that advantage shows up most when the tool is used for advisor matching marketplace. Pricing starts at See website, with a free plan listed as Yes, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is compares fees and specialties. The honest catch is Zoe is a marketplace, not the advisor itself, and a second limit to weigh is advisor fees vary. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Matches clients with vetted advisors
- Compares fees and specialties
- No charge to match
- Zoe is a marketplace, not the advisor itself
- Advisor fees vary
Harness suits people who want a local or in-person advisor option, plus help comparing planners, tax pros and estate specialists in one search. For buyers, the clearest strength is Advisor matching with in-person options in some areas, and that advantage shows up most when the tool is used for advisor matching with local options. Pricing starts at See website, with a free plan listed as Yes, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is tax and planning focus. The honest catch is Advisor fees vary by matched firm, and a second limit to weigh is coverage varies by area. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Advisor matching with in-person options in some areas
- Tax and planning focus
- Advisor fees vary by matched firm
- Coverage varies by area
Ellevest suits women and others who want planning that accounts for pay gaps, career breaks and longer life expectancy, not just a generic retirement age. For buyers, the clearest strength is Goal-based planning, and that advantage shows up most when the tool is used for planning with a gender-aware approach. Pricing starts at See website, with a free plan listed as No, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is salary and career factors in plans. The honest catch is Minimums and fees vary by plan, and a second limit to weigh is smaller than the largest firms. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Goal-based planning
- Salary and career factors in plans
- Investing and coaching options
- Minimums and fees vary by plan
- Smaller than the largest firms
SoFi suits beginners and younger investors who want a low-cost start, free planner access and banking, lending and investing in one app. For buyers, the clearest strength is Low or no minimum on automated investing, and that advantage shows up most when the tool is used for low-cost entry to advice. Pricing starts at See website, with a free plan listed as Yes, so check the current plan page for limits on seats, usage or features before you rely on that price.
What stands out in daily use is access to financial planners. The honest catch is Advice depth is lighter than dedicated firms, and a second limit to weigh is product cross-selling is common. If those limits do not block your main workflow, this is a solid shortlist pick. If they do, move to the next option in this list rather than forcing a tool to fit a job it handles poorly.
- Low or no minimum on automated investing
- Access to financial planners
- Broad SoFi products
- Advice depth is lighter than dedicated firms
- Product cross-selling is common
How we picked these
We compared firm pages and advisor guides for fee models, minimums, planner credentials and planning scope, and we favored firms that publish fees and minimums clearly. This is not financial advice. Investing involves risk, fees can change, and the right advisor depends on your goals, tax position and comfort with risk. Check the firm disclosure before you hire anyone.
How to choose a financial advisor company
First, decide how you want to pay. A percentage fee grows with your portfolio, a flat monthly fee stays steady, and a one-time plan suits people who only need a checkup. A flat fee can be cheaper for larger portfolios, while a low percentage fee can be cheaper for smaller ones, so run both numbers on your balance.
Second, check what planning you actually get. Some firms focus on investments alone, while others cover retirement income, tax, estate, insurance and debt. Ask whether you get a dedicated planner, how often you meet, and whether the planner is a fiduciary for your account. A short intro call should answer those questions clearly.
Sources
- https://facet.com/
- https://investor.vanguard.com/advice/personal-advisor
- https://www.betterment.com/
- https://www.schwab.com/intelligent-portfolios
- https://www.jpmorgan.com/wealth-management/personal-advisors
- https://www.zoefin.com/
- https://www.harnesswealth.com/
- https://www.ellevest.com/
- https://www.sofi.com/
Frequently asked questions
What company is the best financial advisor?
There is no single best firm for everyone. Facet Wealth is a strong flat-fee pick, Vanguard Personal Advisor is a strong low-cost pick for larger portfolios, and Betterment Premium suits investors who want automation plus human advice. Match the fee and minimum to your situation.
How much do financial advisor companies charge?
Models vary. Vanguard Personal Advisor charges a percentage of assets, Facet charges a flat monthly fee, and Betterment Premium and Schwab Premium use percentage fees plus, in Schwab case, a planning fee. Confirm the current fee and what it includes before you sign.
What is the best financial advisor company for retirement planning?
Firms with dedicated retirement planning, such as Vanguard Personal Advisor, Facet Wealth and J.P. Morgan Personal Advisors, suit retirees and near-retirees. Ask how they model retirement income, Social Security, taxes and required distributions.
Do I need a high net worth to hire an advisor?
No. Facet, SoFi and several hybrid firms have no or low minimums, while Vanguard Personal Advisor and Betterment Premium have higher minimums. If your balance is small, a flat-fee or low-minimum firm is usually the better fit.
Should I choose a human advisor or a robo-advisor?
A robo-advisor suits simple, low-cost investing, while a human advisor suits complex taxes, retirement income, business ownership or estate needs. Hybrid firms in this list offer automation plus human planners, which suits many people in between.