Best Pay Later Apps in 2026: 8 Apps Compared
By ToolNimba Editorial Team November 10, 2026 11 min read

- Top pick
 Klarna
Flexible plans and shopping app
Starting priceFreeCheck out KlarnaRead our review - Runner-up
 Affirm
Larger purchases and longer terms
Starting priceFreeCheck out AffirmRead our review - Also great
 Afterpay
Simple Pay in 4 retail shopping
Starting priceFreeCheck out AfterpayRead our review
How we researched this
We compared official pricing and feature pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Klarna offers the widest range of plans, from Pay in 4 to Pay in 30 days and monthly financing.
- Affirm is the strongest pick for larger purchases, with longer terms and no late fees, though interest can apply.
- Afterpay and PayPal Pay in 4 keep the model simple, with four interest-free payments over about six weeks.
- Sezzle and Zip suit smaller, everyday purchases, with different service fees and credit-building options.
- Late fees, interest and credit reporting vary by plan, so read the terms for the exact plan you choose, not just the app.
Quick comparison
| Name | Best for | Starting price | Free plan | |
|---|---|---|---|---|
| Klarna | Flexible plans and shopping app | Free | Yes | Visit |
| Affirm | Larger purchases and longer terms | Free | Yes | Visit |
| Afterpay | Simple Pay in 4 retail shopping | Free | Yes | Visit |
 PayPal Pay Later | PayPal users and Pay in 4 | Free | Yes | Visit |
 Sezzle | Budget shopping and credit building | Free | Yes | Visit |
 Zip | Shopping anywhere Visa is accepted | Free | Yes | Visit |
 Shop Pay Installments | Shopify store shoppers | Free | Yes | Visit |
 Splitit | Using an existing credit card | Free | Yes | Visit |
The best pay later apps
Pay later apps split a purchase into smaller payments, but the details matter. A Pay in 4 plan is often interest-free if paid on time, while a monthly plan can carry interest, and missed payments can bring fees or credit effects. This section is not financial advice. We compared official help pages, fee disclosures, app store listings and public comparisons, with a focus on plan types, fees, late charges, credit checks and store coverage.
Klarna is the most flexible pay later app on this list, because it covers more than one way to pay. Pay in 4 splits a purchase into four interest-free payments, Pay in 30 days lets you defer full payment, and monthly financing covers larger purchases over a longer term. The app also tracks orders, spending and upcoming payments in one place, which helps you avoid a missed instalment.
Flexibility has a cost to watch. Monthly financing can carry interest, and Pay in 4 late fees can apply after a grace period, capped as a share of the order. Klarna suits a shopper who wants options and will check the plan terms before confirming, rather than assuming every plan is interest-free. If you only want Pay in 4, set that plan explicitly at checkout.
- Pay in 4, Pay in 30 days and monthly financing
- Wide store coverage
- Shopping app with price tracking
- Monthly financing can carry APR up to 35.99 percent
- Late fee up to $7 on Pay in 4 after a grace period
Affirm stands out for larger purchases, such as furniture, electronics and travel, where four payments are not enough. You see the total interest cost before you commit, there are no late fees, and terms can stretch far longer than a standard Pay in 4 plan. That transparency helps you compare a monthly plan with saving up or using a credit card.
Interest is the main cost, since APR depends on the retailer, term and your credit profile, and some promotional plans may involve a hard credit check. Affirm also reports loans to credit bureaus, so on-time payments can help and missed payments can hurt. Use Affirm when you need time for a large purchase and the total cost still makes sense.
- No late fees
- Clear total interest shown before you commit
- Terms from months to several years at some retailers
- APR can range from 0 percent to 36 percent
- Some plans may involve a hard credit check
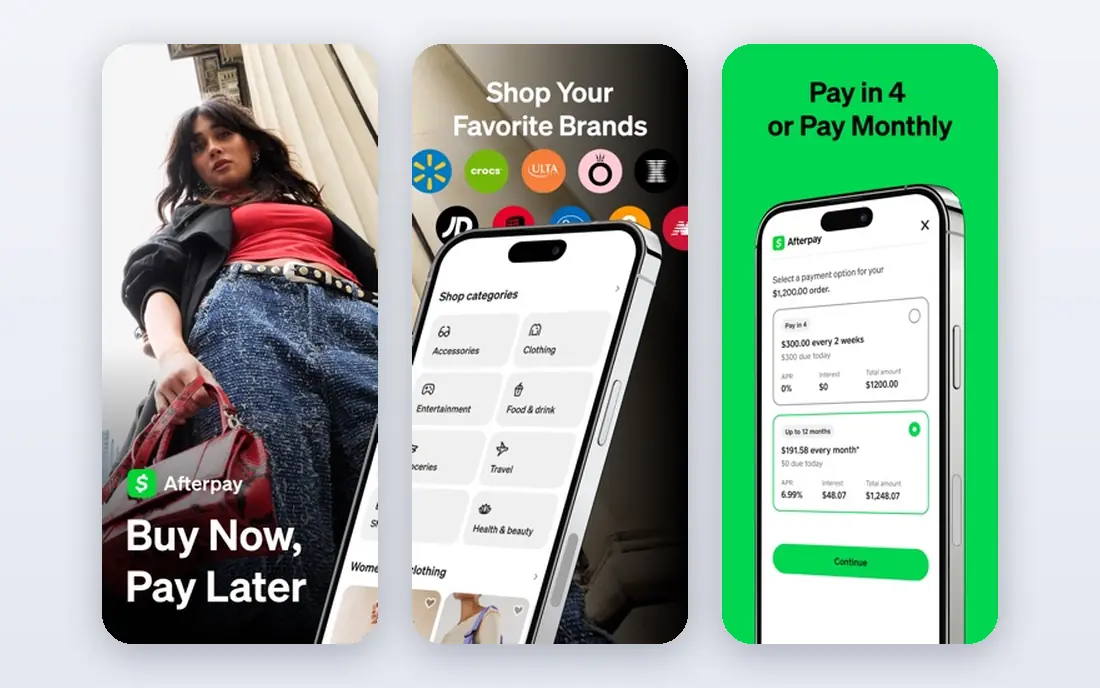
Afterpay keeps pay later simple, splitting a purchase into four equal payments due every two weeks, with no interest if you pay on time. It is especially strong for fashion, beauty and lifestyle retailers, and it is integrated with Cash App for many US shoppers. The app shows upcoming payments clearly, which helps you plan around paydays.
Late fees are the catch, with charges applying after a grace period and capped at 25 percent of the order. Spending limits also vary by customer and merchant, so approval for one purchase does not guarantee the same limit next time. Afterpay suits a shopper who wants a predictable Pay in 4 routine and can meet every biweekly payment.
- Simple four-payment structure
- Interest-free if paid on time
- Strong retail and Cash App coverage
- Late fees capped at 25 percent of the order
- Spending limits vary and are not always clear upfront
PayPal Pay Later is the easiest pay later option if you already use PayPal, since it appears at checkout with retailers that support it. Pay in 4 splits eligible purchases into four interest-free payments with no late fees, while Pay Monthly covers larger purchases over a longer term. That familiarity reduces setup, since many shoppers already have a PayPal account and payment method saved.
Pay in 4 purchase limits are lower than Affirm for large items, and monthly plans can carry interest, so check the plan shown at checkout. PayPal Pay Later suits a shopper who wants a simple, low-fee Pay in 4 option inside a checkout they already trust, rather than a new app for every store.
- No late fees on Pay in 4
- Familiar PayPal checkout
- Monthly plans for larger purchases
- Pay in 4 limit is lower than some rivals
- Monthly plans can carry interest
Sezzle offers interest-free Pay in 4 with a focus on budget-conscious shoppers, plus an optional Sezzle Up feature that reports payment history to credit bureaus. That opt-in reporting can help a shopper build credit with on-time payments, which sets Sezzle apart from apps that do not report Pay in 4 activity by default. Rescheduling can also help if a payday moves, though terms vary.
Service fees can apply on some purchases, and late fees are capped as a share of the order, so the cheapest plan is still the one you pay on time. Sezzle suits a shopper who wants a simple Pay in 4 app and values the option to build credit, provided every payment is made on schedule.
- Interest-free Pay in 4
- Optional Sezzle Up credit reporting
- Rescheduling options on some orders
- Service fees can apply on some purchases
- Late fees capped at 25 percent of the order
Zip, formerly Quadpay, is useful because it is not limited to retailers with a pay later button. It creates a virtual Visa card for a purchase, so you can split payments at many stores that accept Visa, even if they do not list Zip at checkout. That flexibility makes it a good fallback app when your preferred store does not offer Klarna, Affirm or Afterpay.
The cost to check is the per-instalment fee on some orders, plus late fees that vary by state. Zip suits a shopper who wants to use pay later more widely and will compare the total fee for that purchase with other apps. For a store that already offers Pay in 4 directly, a direct option may be cheaper.
- Virtual card works at many stores
- Simple Pay in 4 structure
- Useful where a retailer has no BNPL button
- Per-instalment fees can apply on some orders
- Late fees vary by state and order size
Shop Pay Installments appears inside Shop Pay checkout on Shopify stores, which makes it almost invisible to set up. Pay in 4 is interest-free when paid on time, while monthly instalments cover larger orders with interest that depends on the plan and your profile. Order tracking through the Shop app also helps you follow deliveries and payments together.
Availability is the limit, since it only works where a store offers Shop Pay. Monthly APR can also be higher than some rivals, so read the plan total before confirming a long-term purchase. Shop Pay Installments suits a frequent Shopify shopper who wants a fast, familiar checkout without opening a separate pay later app.
- Smooth checkout on Shopify stores
- Interest-free Pay in 4
- Monthly plans for larger orders
- Only available where Shop Pay is offered
- Monthly plans can carry APR from 10 percent to 36 percent
Splitit works differently from most pay later apps, because it splits a purchase across your existing credit card rather than creating a new loan. You pay in monthly instalments on the card you already hold, with no interest or fees from Splitit itself, and no new credit application through Splitit. That structure appeals to cardholders who want predictable instalments without another account.
The catch is your card terms. If you carry a balance past the due date, your card interest still applies, so Splitit is only cheap if you pay the card on time. Availability also depends on the retailer. Splitit suits a shopper with a card limit and a plan to clear each instalment in full each month.
- No new loan or credit check from Splitit
- Uses your existing card limit
- No interest from Splitit itself
- Your card interest still applies if you carry a balance
- Not available at every retailer
How we picked these
We compared official help pages, fee disclosures, app store listings and public comparisons for apps that operate in the US in 2026 and that a reader can actually use at checkout. A product stayed on the list if it offered a clear Pay in 4 or monthly plan, with terms a shopper could check before buying. We gave weight to fee transparency, late charges, credit reporting, store coverage and ease of tracking payments.
We did not claim hands-on testing we did not do, and fees vary by state, retailer and plan. Instead, we weighed vendor disclosures against independent fee comparisons, and we noted where a plan can carry interest even when the app itself is free to download. That approach helps you compare total cost, not just the headline promise of four payments.
How to use pay later apps without hurting your budget
Pay later works best as a cash flow tool for a purchase you could already afford, not as a way to buy something you cannot. A simple rule helps, which is to only split a purchase if you could pay for it in full today and still cover essentials.
Check the full plan before you tap confirm
Read the number of payments, due dates, interest rate, service fees and late fee for that exact plan. A Pay in 4 plan and a monthly plan from the same app can have very different costs and credit effects. Save a screenshot or note of the plan total, so you can compare it with the cash price.
Track payments like bills, not like free money
Add each instalment to your calendar or budget app, and avoid stacking several pay later plans at once. Multiple biweekly payments can overlap and create a week with far higher outgoings than expected. If a payment date moves, reschedule early through the app rather than waiting for a late fee.
Know the credit and fee risks honestly
Some apps report monthly plans to credit bureaus, some report only with an opt-in, and some do not report standard Pay in 4 activity. Missed payments can still lead to fees, account limits or collections, even when an app charges no late fee. If you miss a payment, contact the provider promptly and check whether a reschedule or hardship option exists.
Sources
Frequently asked questions
What are the best pay later apps for Pay in 4?
Klarna, Afterpay, PayPal Pay Later and Sezzle are strong Pay in 4 picks, with interest-free payments if you pay on time. PayPal Pay Later charges no late fees on Pay in 4, while Klarna, Afterpay and Sezzle have late fees capped as a share of the order.
What is the best app for buy now pay later on large purchases?
Affirm is a strong pick for large purchases, with longer terms, no late fees and a clear total interest cost shown upfront. Shop Pay Installments and Klarna monthly plans are also useful, but compare APR and total cost before choosing a long term.
Do pay later apps affect your credit score?
It depends on the app and plan. Affirm reports loans to bureaus, Klarna reports monthly financing, Sezzle reports only if you opt into Sezzle Up, and standard Pay in 4 activity often is not reported unless it goes to collections. A hard credit check on some longer plans can also affect your score temporarily.
What happens if I miss a pay later payment?
You may face a late fee, a spending limit reduction or account restrictions, depending on the app and plan. Affirm and PayPal Pay in 4 charge no late fees, while Klarna, Afterpay, Sezzle and Zip have capped late fees that vary by order and state.
What are the best split payment apps for shopping anywhere?
Zip is a strong pick for shopping anywhere Visa is accepted, thanks to its virtual card, while Klarna also works widely through its app and card options. Check per-instalment fees for Zip, since a direct Pay in 4 button at a retailer may be cheaper.
What is the best 4 payment app for beginners?
PayPal Pay Later is a good beginner pick if you already use PayPal, with a simple Pay in 4 plan and no late fees. Afterpay is also simple for retail shopping, provided you can meet every biweekly payment on time.