Best Credit Score Apps in 2026: 9 Apps Compared
By ToolNimba Editorial Team October 28, 2026 10 min read

- Top pick
 Credit Karma
Free scores from two bureaus
Starting priceFreeCheck out Credit KarmaRead our review - Runner-up
 Experian
Free FICO score
Starting priceFreeCheck out ExperianRead our review - Also great
 WalletHub
Daily updates and full report
Starting priceFreeCheck out WalletHubRead our review
How we researched this
We compared official pricing and feature pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Credit Karma, WalletHub, and Credit Sesame all offer a free score and monitoring, but they show different score models and bureaus.
- Experian is the best free option if you want a FICO score, since most free apps show a VantageScore instead.
- myFICO is the pick before a mortgage or auto loan, because it shows FICO scores from all three bureaus on paid plans.
- Checking your own score through these apps is a soft inquiry and does not lower your score.
- Paid plans add three-bureau reports, identity protection, and faster updates, but most people do not need them every month.
Quick comparison
| Name | Best for | Starting price | Free plan | |
|---|---|---|---|---|
| Credit Karma | Free scores from two bureaus | Free | Yes | Visit |
| Experian | Free FICO score | Free | Yes | Visit |
| WalletHub | Daily updates and full report | Free | Yes | Visit |
 Credit Sesame | Simple free monitoring | Free | Yes | Visit |
 myFICO | FICO scores before a big loan | Free | Yes | Visit |
 CreditWise | Capital One customers and others | Free | Yes | Visit |
 Chase Credit Journey | Chase customers and others | Free | Yes | Visit |
 Discover Credit Scorecard | Free FICO score without a card | Free | Yes | Visit |
 NerdWallet | Scores plus broader money tools | Free | Yes | Visit |
The best credit score apps
We compared official feature pages, app store listings, privacy pages, and public reviews for apps that are live in the US. We focused on which bureau and score model each app shows, how often it updates, and what the paid plan adds. This is not financial advice, and a free educational score can differ from the score a lender pulls.
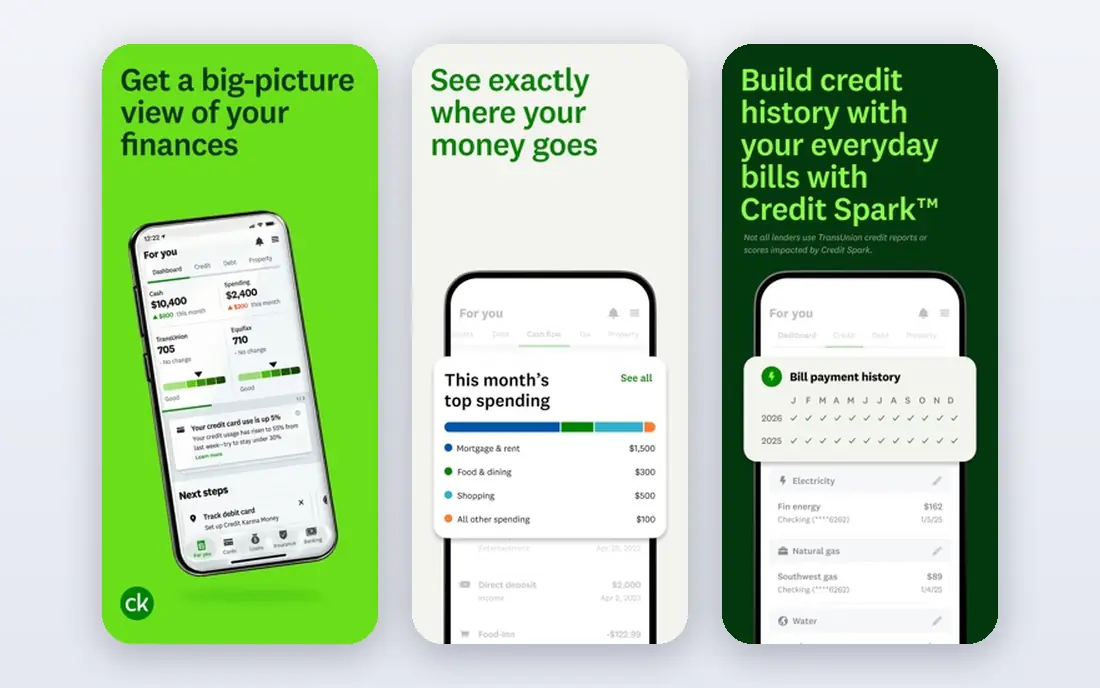
Credit Karma is our pick for most people who want a free score check without paying. It shows VantageScore 3.0 scores from Equifax and TransUnion, with credit monitoring, alerts for changes, and a report summary. The app also adds budgeting, savings, and tax tools, which can help if you want one place for basic money tasks.
The catch is the business model. Credit Karma is free because it shows card and loan offers, so expect recommendations in the feed. Its scores can also differ from a lender FICO score, so treat the number as a guide, not as a promise of approval or a rate.
- Free VantageScore scores from Equifax and TransUnion
- Credit monitoring and alerts
- Tax and money tools in the same app
- No Experian score
- Heavy card and loan offers
- Score is VantageScore, not FICO
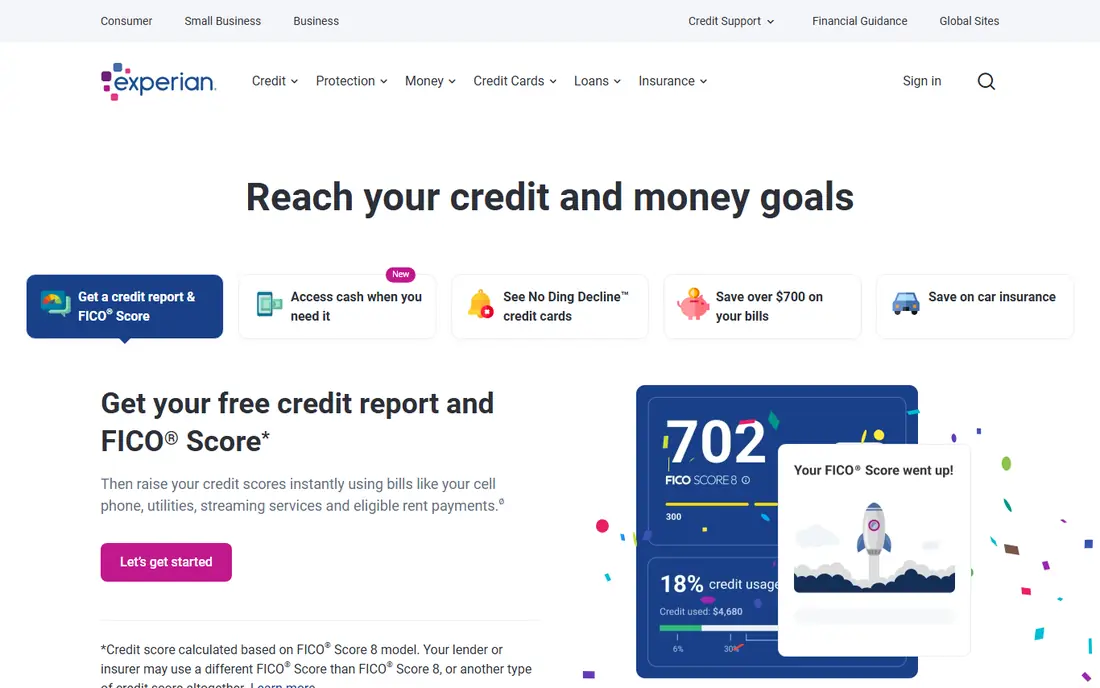
Experian stands out because it is a bureau itself, and its free app shows a FICO 8 score rather than a VantageScore. That makes it closer to the number many lenders use, at least for the Experian report. Experian Boost can add utility, phone, and streaming payments to your Experian file, which may raise that score for some users.
Paid plans are the upsell to watch. CreditWorks Premium adds FICO scores from all three bureaus and identity protection for about $24.99 per month in the sources we checked. Most people can start free, check monthly, and only pay for a short period before a major application.
- Free FICO 8 score from Experian
- Experian Boost for utility and streaming payments
- Dark web scan on the free tier
- Paid CreditWorks plans cost $24.99 per month or more
- Boost affects only the Experian score
WalletHub is useful if you want frequent updates without paying. Its free tier shows a TransUnion VantageScore and a full report, updated daily, with monitoring and a personalized improvement plan. That daily view helps you spot a new account, a missed payment, or an error sooner than a monthly check.
The limit is bureau coverage. WalletHub free shows TransUnion, not all three bureaus, so an error on Equifax or Experian could stay hidden. Pair it with Credit Karma or Experian if you want a wider view without paying for a three-bureau plan.
- Daily score and report updates
- Full TransUnion report
- Credit monitoring and improvement tips
- Shows TransUnion only on the free tier
- Paid plan adds features many users will not need
Credit Sesame is a good pick if you want a simple, low-noise score check. The free tier shows a TransUnion VantageScore with monitoring and basic insights, without the heavier offer feed found in some rivals. Its debt tools can also help you see how balances and payments affect your score over time.
It is not a full three-bureau tool for free. If you need Equifax and Experian scores, or a detailed report for a dispute, you will need another app or a paid plan. Use Credit Sesame as a daily or weekly check, not as your only source before a loan.
- Free TransUnion VantageScore
- Simple alerts
- Debt and money tools in the same app
- Free score covers one bureau
- Paid Sesame Plus adds cost
- Fewer report details than some rivals
myFICO is the app to check before a mortgage, auto loan, or other large application, because it comes from the company behind the FICO model. Paid Advanced and Premier plans show FICO scores from Equifax, Experian, and TransUnion, with updates and loan-specific versions that match what lenders often use. That detail can matter when a small score change affects your rate.
The price is the reason not to keep it year-round. Advanced costs about $29.95 per month and Premier about $39.95 per month in the sources we checked, so use it for a month or two around an application, then cancel if you no longer need it. The free tier alone is not a substitute for the paid three-bureau view.
- Real FICO scores from all three bureaus on paid plans
- Loan-specific scores for mortgages and auto loans
- Identity protection on paid tiers
- Paid plans cost $29.95 per month or more for full three-bureau cover
- Free tier is limited to one bureau
CreditWise from Capital One is free to anyone, not just Capital One cardholders, and it shows a TransUnion VantageScore with weekly updates. It also includes credit monitoring, alerts, and a dark web scan, which makes it a solid second app for spotting changes. The interface is clear, and it does not push a paid tier as hard as some rivals.
Its limit is the same as most free apps: one bureau and one score model. That is fine for routine tracking, but it will not show an Experian or Equifax problem. Use it alongside Experian if you want both a VantageScore and a FICO view for free.
- Free TransUnion VantageScore
- Weekly updates
- Dark web monitoring and alerts
- No Capital One card needed
- Shows one bureau
- Score is VantageScore, not FICO
- Fewer money tools than Credit Karma
Chase Credit Journey is free to anyone, and it shows a TransUnion VantageScore with weekly updates and monitoring. It explains the factors behind your score, such as payment history and utilization, in plain terms, which helps new credit users understand what to fix first. Identity monitoring and alerts add value without a subscription.
Chase customers get a tighter fit with their bank app, but non-customers can still use the standalone tool. Like CreditWise, it covers one bureau, so pair it with a second free app if you want broader coverage.
- Free TransUnion VantageScore
- Weekly updates
- Credit monitoring and identity tools
- No Chase account needed
- Shows one bureau
- Score is VantageScore
- Some features are stronger for Chase customers
Discover Credit Scorecard
Best for: Free FICO score without a card
Discover Credit Scorecard is a quiet but useful free option, because it shows a FICO 8 score from Experian without requiring a Discover card. That gives you a lender-relevant number for free, with a score history you can track over time. It is a good backup to Experian itself if you want a second FICO view.
Updates are monthly on the free tier, so it is less useful for spotting a sudden change the same week. It also lacks the deeper three-bureau monitoring found in paid plans. Use it for monthly trend tracking, and use WalletHub or Credit Karma for faster alerts.
- Free FICO 8 score from Experian
- No Discover card needed
- Simple score history
- Shows one bureau
- Monthly updates on the free tier
- Fewer monitoring extras than paid tools
NerdWallet fits readers who want a credit score inside a wider money app. Its free tier shows a TransUnion VantageScore, with monitoring and explanations, alongside budgeting, net worth tracking, and card and loan comparisons. That context helps if you are also choosing a card or planning a payoff.
It is not the fastest monitoring tool. WalletHub updates daily, while NerdWallet updates less often, so a new account may appear later here. Use NerdWallet for the broader money view, and keep a daily or weekly monitor running elsewhere if timing matters.
- Free TransUnion VantageScore
- Budgeting and account tracking
- Clear explanations of score factors
- Score updates less often than WalletHub
- Paid tools are limited
- Offers appear alongside free tools
How we picked these
We compared official feature pages, app store listings, privacy pages, and public reviews for apps that show a real credit score in the US. We checked which bureau each app uses, whether the score is FICO or VantageScore, how often it updates, and what the free tier actually includes. We kept only apps that are free to start, live today, and useful without a paid plan, and we noted where a paid plan is needed for three-bureau cover.
How to use a free score without overpaying
Start with two free apps that cover different bureaus and models, such as Experian for a FICO score and Credit Karma or WalletHub for VantageScore views. Check them on a set schedule, such as weekly, and look for new accounts, missed payments, and utilization changes. A small score move from normal use is normal, so focus on trends and on errors, not on a single point change.
Next, fix the factors you control before you pay for anything. Pay on time, keep card balances low relative to limits, and avoid opening several new accounts in a short period. If you find an error, dispute it directly with the bureau that shows it, using the report detail in the app, and keep copies of your dispute.
Finally, pay for a three-bureau FICO plan only around a major application, such as a mortgage. Subscribe, check the loan-specific scores, then cancel when the application is done. A monthly paid plan year-round rarely adds value for routine tracking.
Sources
- https://www.creditkarma.com
- https://www.experian.com
- https://www.wallethub.com
- https://www.creditsesame.com
- https://www.myfico.com
- https://www.creditwise.com
- https://www.chase.com
- https://www.discover.com
- https://www.nerdwallet.com
- https://wallethub.com/blog/credit-sesame-vs-credit-karma-vs-wallethub/19158
- https://pocketguard.com/blog/best-credit-score-apps/